September 2026 Market Commentary

Insights for Municipal Investors & Issuers

By Brian Johnson, Director of Investment Services
and Brian Reilly, Senior Municipal Advisor | Managing Director

With summer firmly in the rearview mirror, financial markets are entering the final stretch of the year, balancing a still-healthy economy against inflation pressures that continue to influence interest rate expectations. Those broad forces converged last week as the Federal Reserve’s Federal Open Market Committee (FOMC) increased the target range for the federal funds rate by 25 basis points (0.25%) to 3.75%–4.00%. The decision was unanimous among voting members and represented a shift from an earlier wait-and-see posture.

In a statement released upon conclusion of its September 16th meeting, the FOMC described economic activity as “expanding at a solid pace, supported by resilient domestic spending, strong productivity growth, and robust capital investment.” At the same time, they continued to emphasize that inflation remains elevated above their 2.0% target.

Recent price data helps explain the Fed’s decision to modestly tighten its policy stance. The Consumer Price Index (CPI) rose 0.4% in August, representing a 3.4% increase year over year. Energy remained an important contributor, with gasoline prices rising 3.9% in August. Core CPI, which excludes food and energy, increased 0.3% in August and 2.4% versus one year prior.

A firm labor market gave the FOMC room to keep its focus on price stability and its long-term inflation target. Employers added 162,000 jobs in August, while the unemployment rate held at 4.1%. The August jobs data showed a marked improvement over the revised July number of 21,000 jobs.

Consumer spending has largely driven the U.S. economy over the past several months, and August retail sales data reinforced that trend. Retail and food-service sales increased 1.2% in August and were 6.0% above August 2025 levels, according to a recent U.S. Commerce Department data release.

At the time of this update, the 1-year Treasury yield was 4.39%, the 2-year was 4.68%, and the 10-year yield was just shy of 5.00%. Even after the increase in the fed funds rate, overnight rates still remain meaningfully below short-to-intermediate yields.

For public funds investors, higher yields across yield curve improve the income potential on high-quality fixed-income investments by selectively extending duration. This also provides a higher level of certainty related to interest income when budgeting. It’s true that short-term vehicles such as money market funds and Local Government Investment Pools (LGIPs) continue to offer reasonably attractive yields, which will likely improve nominally as reinvestment in those underlying portfolios unfolds. However, those yields will remain highly sensitive to future FOMC decisions and can change quickly as monetary policy expectations evolve.

We believe cash-flow forecasting remains the foundation of an effective investment strategy. Clearly identifying operating liquidity, near-term expenditures, and funds that can be invested beyond immediate needs can help governmental entities take advantage of higher yields without compromising safety or liquidity.

For funds not needed in the near term, selectively extending maturities may provide greater income stability and reduced reinvestment risk. This approach can provide more predictable investment income across budget cycles while preserving regular access to principal as investment positions mature.

The borrower perspective presents a different set of considerations in the current interest-rate environment. While most economies can generally withstand a broad increase in prevailing interest rates, even a substantial one, the pace of that increase is often more consequential than the magnitude alone.  As noted in the table below, benchmark Treasury maturities are up 60–110+ basis points over the prior one-year period. However, a large proportion of this increase has materialized in the last 30 days.
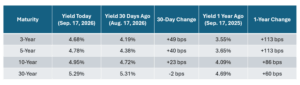
The yield curve is also flattening. Short and intermediate maturities have increased more than longer-term maturities. In the last month, yields from 1–5 years are up 40–50 basis points, while the 30-year has declined nominally. This reflects the market’s current view that the FOMC will maintain a tightening bias, which is primarily expressed at the shorter end of the yield curve.

The tax-exempt municipal market doesn’t always march to the drum of U.S. Treasuries, as municipals represent a distinctly different and largely domestic universe of buyers. Municipals have not been as volatile as Treasuries but have generally followed a similar path at all maturities.

Since the beginning of September, broad measures of high-quality municipal bond yields are up 20–25 basis points across the maturity spectrum. This recent backdrop has also diminished demand. Lipper reported $1.8 billion of outflows from municipal bond funds the week of this publication, breaking a five-month-long streak of inflows. Outflows have been the most pronounced in high-yield funds with lower-quality credits. There have been weeks with new issue supply in the range of $12–$16 billion, which exceeds recent averages under $10 billion. The rapid rise in yields has had the greatest impact on lower-quality credits, resulting in materially higher credit spreads than at the start of the year.

While borrowing costs are certainly up, it’s worthwhile to examine results in some of Ehlers’ core markets. In the last two weeks our clients have priced both competitive and negotiated transactions. Competitive sales can often provide a strong barometer of dealer and investor sentiment during periods of volatility.

Strong credits have priced well on a historical basis. A recent sale of tax-exempt, bank-qualified G.O. Bonds by a AA+ rated Minnesota City with a 20-year term received 10 bids with a True Interest Cost (TIC) of 3.99%. A smaller AA issue with a 15-year term garnered seven bids and priced with a TIC of 3.98%. A Wisconsin AAA-rated issuer sold both tax-exempt and taxable issues concurrently. The tax-exempt issue was non-BQ, had a 20-year term, and received six bids with a winning TIC of 4.19%. The taxable series was shorter at 10 years, received four bids, and was awarded at a TIC of 5.09%.

These results remain constructive, but market volatility has made investors more selective. Lower-credit issuers are bearing more of the burden and should give additional attention to market access, debt structure, and method of sale.  Headlines around “increased” rates are far more indicative of activity around the shorter end of the interest rate curve.  Governmental entities are generally long-term borrowers where costs remain reasonable on a historical basis.  Additionally, incorporating a reinvestment and arbitrage strategy into your borrowing plan can be highly effective at lowering net interest cost.

Setting proper expectations with your Municipal Advisor is important at moments like these. Attempting to time the market is generally a futile effort. All options should be evaluated based on the nature of the financing and the needs of the issuer.

Several factors are likely to shape the interest-rate outlook through the remainder of 2026, including geopolitical developments that affect global supply chains and commodity prices, the market’s perception of FOMC decisions regarding overnight rates, and whether the resilience of the labor market and consumer continues over the near and medium terms.

The appropriate debt and investment strategy varies by entity and your specific needs. If you are interested in discussing your current debt or investment needs, reviewing cash-flow assumptions, or exploring alternative investment strategies, please contact your Ehlers Municipal Advisor or Investment Adviser to schedule some time to discuss.

Required Disclosures: Please Read

Ehlers is the joint marketing name of the following affiliated businesses (collectively, the “Affiliates”): Ehlers & Associates, Inc. (“EA”), a municipal advisor registered with the Municipal Securities Rulemaking Board (“MSRB”) and the Securities and Exchange Commission (“SEC”); Ehlers Investment Partners, LLC (“EIP”), an investment adviser registered with the SEC; and Bond Trust Services Corporation (“BTS”), holder of a limited banking charter issued by the State of Minnesota.

This communication does not constitute an offer or solicitation for the purchase or sale of any investment (including without limitation, any municipal financial product, municipal security, or other security) or agreement with respect to any investment strategy or program. This communication is offered without charge to clients, friends, and prospective clients of the Affiliates as a source of general information about the services Ehlers provides. This communication is neither advice nor a recommendation by any Affiliate to any person with respect to any municipal financial product, municipal security, or other security, as such terms are defined pursuant to Section 15B of the Exchange Act of 1934 and rules of the MSRB. This communication does not constitute investment advice by any Affiliate that purports to meet the objectives or needs of any person pursuant to the Investment Advisers Act of 1940 or applicable state law. In providing this information, The Affiliates are not acting as an advisor to you and do not owe you a fiduciary duty pursuant to Section 15B of the Securities Exchange Act of 1934. You should discuss the information contained herein with any and all internal or external advisors and experts you deem appropriate before acting on the information.
Getting Pay ’27 Right

What Minnesota School Business Officials Need to Know

By Aaron Bushberger, Senior Municipal Advisor
and Shelby McQuay, Senior Municipal Advisor | Managing Director


Every fall, Minnesota school districts certify a property tax levy driven by statutory formulas and allowances and enrollment estimates that determine how much local taxpayers contribute to school operations and debt repayment for the year ahead. And every fall, a handful of avoidable  errors ripple forward into future levies, producing swings that districts must then explain to property owners.

The Pay 27 cycle is no different. With August reporting requirements now in the rearview and certification in full swing, it’s worth revisiting how the levy is actually calculated, where errors tend to creep in, and what districts can do now to protect accuracy.

We encourage you to reach out to your Ehlers advisors if you have questions about your levy or would just like another set of eyes on your report.  Our advisors routinely assist districts with levy review and strategy, including providing districts with preliminary tax base from your counties and giving you an initial look at the estimated tax impact of your Pay 27 levy.

Two Tax Bases, One Equation

School district levies are spread across two different tax bases, which is the first source of confusion for anyone trying to explain a tax bill. The underlying math, though, is simple: the tax rate is the corresponding levy divided by the corresponding tax base.

That simplicity is deceptive. Both sides of the equation move. The levy changes as enrollment, debt schedules, and statutory formulas shift. The tax base changes as property values rise and fall across residential, agricultural, commercial, and industrial classifications. A district can hold its levy flat and still see rates (and thus taxes) move, or grow its levy and see rates fall, depending entirely on what happened to the base. Understanding which variable drove the change is essential before a district tries to communicate the outcome to its community.

What Actually Shapes the Calculation

Two factors dominate. The first is enrollment data — both students served and resident students. The second is debt service, meaning the district’s annual repayment obligations.

Beyond those primary drivers sit a set of additional factors that shape individual levy components: actual expenditures, building age, the population of the district, voter approval, and unique programs like career and technical education. Each of these feeds particular authorities, which is why two districts of similar size can end up with meaningfully different levies.

The Three-Step ADM Adjustment

Average daily membership deserves special attention because of how the adjustment mechanism works.

The Pay 27 levy is initially calculated using an estimate of next year’s ADM — the 2027-28 school year. That estimate is then adjusted based on first prior year ADM estimates from 2026-27 and adjusted again using final third prior year ADM from 2024-25. In other words, a single enrollment estimate touches the levy three separate times across multiple cycles.

This is precisely why significantly overestimating or underestimating enrollment is costly. An enrollment miscalculation doesn’t simply correct itself quietly. It triggers adjustments, and those adjustments produce property tax swings that land on taxpayers in a later year, disconnected from the decision that caused them.

Resident ADM plays a related but distinct role: it determines the state aid and local levy mix for equalized funding formulas. Get resident ADM wrong and a district misallocates between state and local shares — again with downstream consequences.

Debt Service

Debt service levies are set at 105% of scheduled debt service payments, with the cushion accounting for collection shortfalls. Where districts anticipate future bond issues — say, facilities maintenance bonds to be issued next spring to fund a summer 2027 roofing project — estimates are built into the calculation.

Because existing debt and potential future issuances both feed this calculation, verification of debt levy figures is one of the highest value reviews a district can perform before certification, which is another reason we cross-check this on your behalf.

The Bottom Line

School district levies are complicated — that is the honest starting point for any conversation with a school board or a taxpayer. Accurate estimates matter not only because they shape the current levy, but because they reverberate into future ones through the adjustment mechanism.

Districts that invest time in a year-over-year comparison, verify their debt figures, and pressure-test their enrollment assumptions before deadlines arrive spend far less time explaining surprises later.

Have questions or need assistance with your interpreting your district’s levy or preparing your annual TNT presentation?  Use the link below to contact us or sign up for TNT services today!

Required Disclosures: Please Read

Ehlers is the joint marketing name of the following affiliated businesses (collectively, the “Affiliates”): Ehlers & Associates, Inc. (“EA”), a municipal advisor registered with the Municipal Securities Rulemaking Board (“MSRB”) and the Securities and Exchange Commission (“SEC”); Ehlers Investment Partners, LLC (“EIP”), an investment adviser registered with the SEC; and Bond Trust Services Corporation (“BTS”), holder of a limited banking charter issued by the State of Minnesota.

This communication does not constitute an offer or solicitation for the purchase or sale of any investment (including without limitation, any municipal financial product, municipal security, or other security) or agreement with respect to any investment strategy or program. This communication is offered without charge to clients, friends, and prospective clients of the Affiliates as a source of general information about the services Ehlers provides. This communication is neither advice nor a recommendation by any Affiliate to any person with respect to any municipal financial product, municipal security, or other security, as such terms are defined pursuant to Section 15B of the Exchange Act of 1934 and rules of the MSRB. This communication does not constitute investment advice by any Affiliate that purports to meet the objectives or needs of any person pursuant to the Investment Advisers Act of 1940 or applicable state law. In providing this information, The Affiliates are not acting as an advisor to you and do not owe you a fiduciary duty pursuant to Section 15B of the Securities Exchange Act of 1934. You should discuss the information contained herein with any and all internal or external advisors and experts you deem appropriate before acting on the information.

Tender Offer Refunding

Spotlight on Wayzata Public Schools

By Matthew Hammer, Senior Municipal Advisor
and Beth Downes, Municipal Advisor

Debt service savings are not driven solely by falling interest rates. Ehlers continually reviews market conditions and outstanding debt structures to identify opportunities that can produce savings in all interest rate environments.

Whether a refunding creates value depends on the full economics of the transaction, not just headline interest rates. Higher market yields can reduce the price of outstanding bonds and create opportunities to repurchase debt at a discount to face value.  In a traditional refunding, the bonds being refinanced are called, or “repurchased,” from investors at face value.

These pricing dynamics can become especially meaningful on larger bond issues, where even modest shifts can translate into substantial savings.

In this case, the analysis showed the potential for more than 5% present value savings, making the strategy worth serious consideration.

Wayzata Public Schools issued its taxable Series 2021A advance refunding bonds at a time when taxable rates were favorable. Today, however, a different market environment, combined with the coupon structure of those prior bonds, created a new opportunity to generate savings through a voluntary tender offer to bondholders.

Wayzata Public Schools Explores Tender Offer Refunding to Capture Debt Service Savings

Wayzata Public Schools had more than its historic school bond referendum underway this past spring. Executive Director of Finance and Operations Trevor Peterson, D.A. Davidson & Co., and Ehlers presented the Board with a voluntary tender offer strategy designed to generate millions of dollars in debt service savings by taking advantage of current market conditions. While coordinated alongside the election, the strategy carried some uncertainty because bondholder participation was voluntary and could not be guaranteed in advance.

A tender offer refunding occurs when an issuer offers to purchase its own bonds back from bondholders in the secondary market. The district repurchases those bonds “tendered” by the existing bondholders accepting the offer and cancels them from its outstanding debt obligations. The repurchase cost of bonds tendered can be financed with new refunding bonds, while bonds not tendered remain outstanding and continue to be paid according to existing terms. From a tax perspective, this structure is treated as a current refunding, distinguishing it from advance refundings that are now largely required to be issued as taxable obligations.

Background: The 2021A Refunding Bonds

In 2021, Wayzata Public Schools advance refunded its Series 2014A and 2014B bonds through the issuance of $132.9 million in Taxable General Obligation School Building and Alternative Facilities Refunding Bonds. Even though 2021 bonds were taxable, the refunding produced savings at the time but were not callable until February 1, 2029. Only the maturities from 2030 through 2036 were subject to call and prior redemption at face value, and those callable maturities carried relatively low interest rates, ranging from approximately 1.65% to 2.30%.

The Process

Under the proposed strategy, the District launched a formal voluntary tender offer directed at the 2021A bondholders.  Bondholders had the option to sell their bonds back to the District at a specified price on a specific date. Once responses were received by the stated deadline, the District could identify which maturities and total amount of the outstanding bonds could be repurchased through the tender offer.

To fund the purchase of the tendered bonds, Wayzata issued new, tax‑exempt general obligation bonds. The debt service on the new bonds replaced the debt service previously associated with the tendered taxable bonds, while retaining the original call date of February 1, 2029, on the remaining callable maturities of the 2021A Bonds. Preserving the call date ensured the District maintained the flexibility to pursue a traditional refunding if interest rates became favorable in the future.

Why Savings Are Possible

Several factors contributed to the potential cost savings from the voluntary tender offer. First, changes in interest rates since 2021 affected market pricing of these low-coupon taxable bonds, allowing the outstanding maturities to be repurchased at a discount to face value. This reduced the amount needed to redeem the tendered bonds well below their face value, which similarly reduced the amount of bonds that needed to be issued to affect the tender. Second, the new refunding bonds were issued at tax‑exempt interest rates which helped lower the overall debt service costs.

However, the level of savings was highly dependent on the level of bondholder participation and how the participation was distributed across the maturity and coupon schedule. Not all bondholders accepted the tender offer, and participation varied by maturity, directly influencing how much debt could be refunded and at what cost to the district.

Prior to the formal tender offer, participation assumptions showed a range of outcomes. At 20% uniform participation across maturities, net present value savings were estimated at about $1.1 million. At 30% uniform participation, net present value savings could increase to approximately $1.9 million.

Estimated Impact for Wayzata

Ultimately the district received 38.15% participation by bondholders amounting to $40.01 million of principal.  The combination of the net savings the District achieved by repurchasing the tendered bonds with the issuance of new tax-exempt debt resulted in future debt service savings of $3.08 million.

Other Considerations

As with any financial undertaking, actual results depend on several variables, including market interest rates at the time of pricing, the distribution of tendered bonds by maturity, and the final level of investor participation, none of which could have been known in advance. The District was also aware that it would incur certain upfront costs, such as fees for rating agency review and an information agent that provides details with respect to existing bondholders that are otherwise anonymous to the issuer.  The remainder of costs were largely contingent on successful execution of the various legs of the transaction.

Despite these uncertainties, the potential magnitude of the savings prompted Wayzata Public Schools a rare chance to reduce costs while preserving future flexibility.

Although the District did not directly tie this opportunity to its referendum communications, the strategy was indirectly connected to the broader financing plan because of the District’s debt structure.

The strategy also reflects the added value Ehlers brought to the District by identifying a complex, market-driven opportunity that might otherwise have gone unexplored.

Throughout the process, Ehlers worked closely with District leadership and the finance committee to explain the structure, evaluate the risks, and support informed decision-making.

That collaborative approach reflected both Wayzata Public Schools’ thoughtful leadership and Ehlers’ strategic guidance, underscoring the strength of the partnership and the District’s confidence in pursuing a creative opportunity to generate meaningful savings for taxpayers.


Required Disclosures: Please Read

Ehlers is the joint marketing name of the following affiliated businesses (collectively, the “Affiliates”): Ehlers & Associates, Inc. (“EA”), a municipal advisor registered with the Municipal Securities Rulemaking Board (“MSRB”) and the Securities and Exchange Commission (“SEC”); Ehlers Investment Partners, LLC (“EIP”), an investment adviser registered with the SEC; and Bond Trust Services Corporation (“BTS”), holder of a limited banking charter issued by the State of Minnesota.

This communication does not constitute an offer or solicitation for the purchase or sale of any investment (including without limitation, any municipal financial product, municipal security, or other security) or agreement with respect to any investment strategy or program. This communication is offered without charge to clients, friends, and prospective clients of the Affiliates as a source of general information about the services Ehlers provides. This communication is neither advice nor a recommendation by any Affiliate to any person with respect to any municipal financial product, municipal security, or other security, as such terms are defined pursuant to Section 15B of the Exchange Act of 1934 and rules of the MSRB. This communication does not constitute investment advice by any Affiliate that purports to meet the objectives or needs of any person pursuant to the Investment Advisers Act of 1940 or applicable state law. In providing this information, The Affiliates are not acting as an advisor to you and do not owe you a fiduciary duty pursuant to Section 15B of the Securities Exchange Act of 1934. You should discuss the information contained herein with any and all internal or external advisors and experts you deem appropriate before acting on the information.

ADA Title II Compliance for Local Governments

Implementation Deadline Extended One-Year

By Kristin Cummings, Director of Marketing & Communications


On April 20, 2026, the U.S. Department of Justice announced a one‑year extension of the compliance deadlines for web content and mobile application accessibility, revising the regulation that implements Title II of the Americans with Disabilities Act.

State and local governments with populations of 50,000 or more now have until April 26, 2027, to comply with these regulatory requirements. Public entities with total populations less than 50,000, as well as any special district governments, have until April 26, 2028, to comply.

We recognize that several of our larger client communities have already implemented the required Title II web and mobile application accessibility elements, and Ehlers will continue to support those efforts by delivering fully accessible public facing documents.

While this extension offers a measure of relief for our smaller client communities with more limited staff and financial resources to meet Title II requirements, Ehlers will continue implementing solutions and best practices to ensure all our clients’ public facing documents comply with the regulation.

If you have any questions, please reach out to your municipal advisor.

Required Disclosures: Please Read

Ehlers is the joint marketing name of the following affiliated businesses (collectively, the “Affiliates”): Ehlers & Associates, Inc. (“EA”), a municipal advisor registered with the Municipal Securities Rulemaking Board (“MSRB”) and the Securities and Exchange Commission (“SEC”); Ehlers Investment Partners, LLC (“EIP”), an investment adviser registered with the SEC; and Bond Trust Services Corporation (“BTS”), holder of a limited banking charter issued by the State of Minnesota.

This communication does not constitute an offer or solicitation for the purchase or sale of any investment (including without limitation, any municipal financial product, municipal security, or other security) or agreement with respect to any investment strategy or program. This communication is offered without charge to clients, friends, and prospective clients of the Affiliates as a source of general information about the services Ehlers provides. This communication is neither advice nor a recommendation by any Affiliate to any person with respect to any municipal financial product, municipal security, or other security, as such terms are defined pursuant to Section 15B of the Exchange Act of 1934 and rules of the MSRB. This communication does not constitute investment advice by any Affiliate that purports to meet the objectives or needs of any person pursuant to the Investment Advisers Act of 1940 or applicable state law. In providing this information, The Affiliates are not acting as an advisor to you and do not owe you a fiduciary duty pursuant to Section 15B of the Securities Exchange Act of 1934. You should discuss the information contained herein with any and all internal or external advisors and experts you deem appropriate before acting on the information.